Editorial team ·
Withdrawal timing: request, approval and receipt need separate evidence
Updated:
A withdrawal timing statement needs an identifiable start and finish. “Requested,” “approved,” “sent” and “available” can refer to different events. Britain’s Gambling Commission discusses the whole request in a 2023 blog, which makes it a useful example of why an approval-only reading can change the period being described.
The source starts at the request
The 17 July 2023 blog says data from some large firms show around 99% of customer withdrawal requests approved, processed and fulfilled within 24 to 48 hours of the request being made. The starting point in that sentence is the request, rather than a later approval notice.
The introduction discusses customers waiting for funds to become available. A statement about an operator marking a transfer as sent is not automatically evidence of receipt at the destination. The meaning of the applicable status needs to come from the actual provider’s terms and record.
The blog does not provide a particular customer’s request timestamp, destination bank or transfer confirmation. Consequently, it cannot establish the arrival date of a request made on a Friday, or whether a separate policy’s “two days” means calendar or business days.
A useful chronology keeps unknown times blank
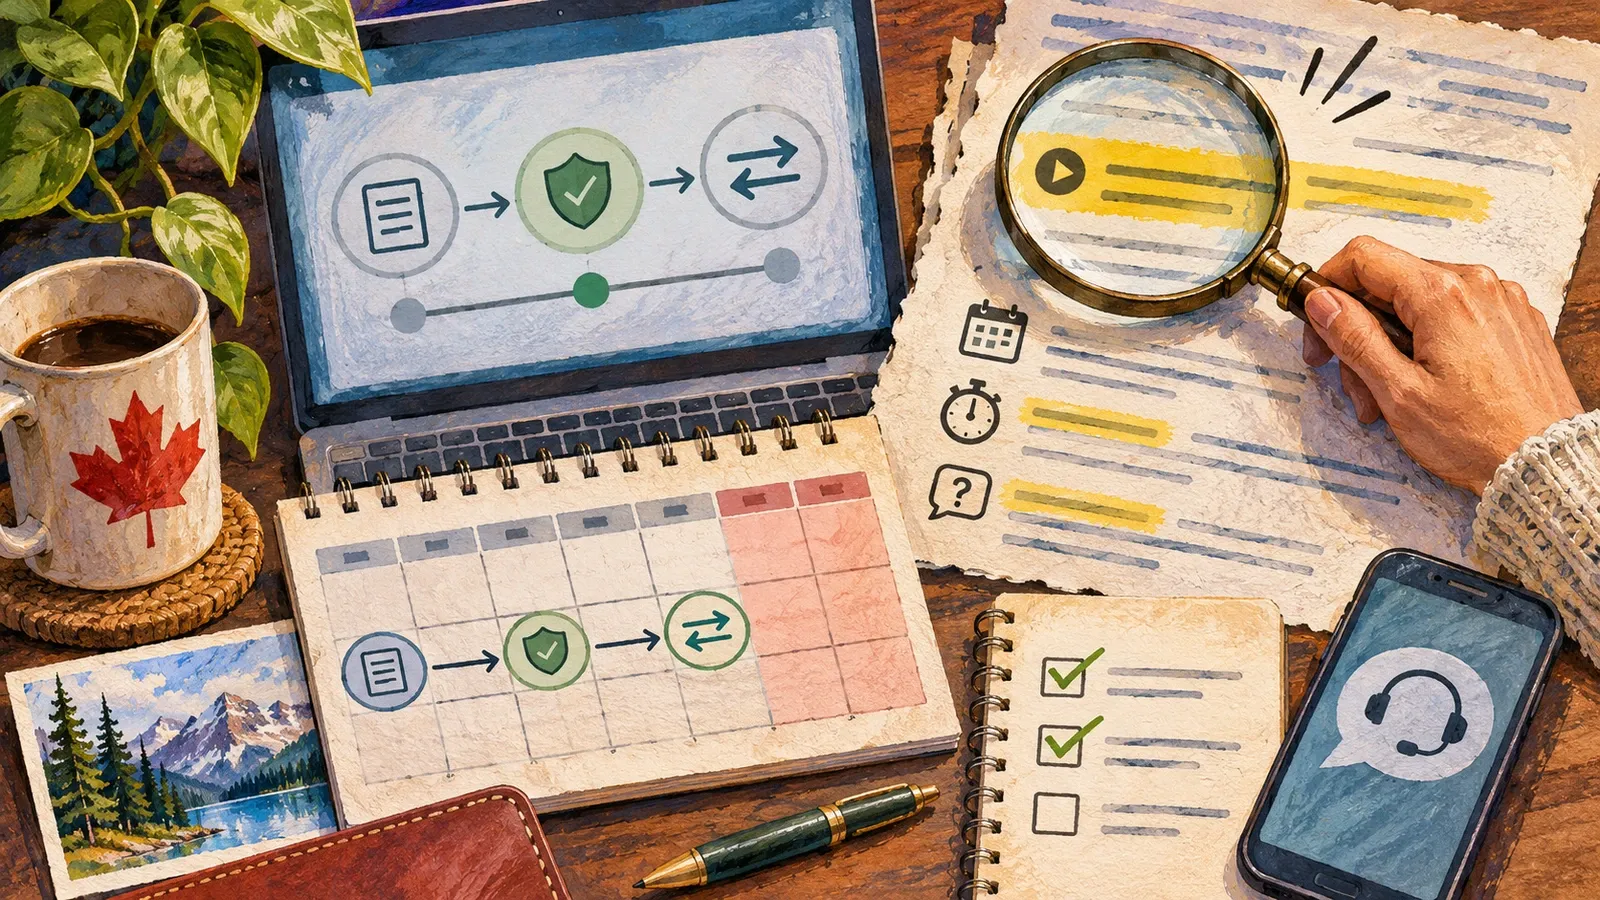
| Event | Evidence to match | Not supplied by the cited blog |
|---|---|---|
| Request made | The request confirmation and applicable starting clause | A particular customer’s time and reference |
| Approved or sent | The provider’s status definition and corresponding record | Whether that status means completion |
| Funds received | The relevant destination record | A personal bank arrival time |
This is an unfilled reading aid, not a report of a withdrawal completed for this website. It does not collect account information. A complete private chronology can later show the intervals that actually occurred without filling gaps with a fictional Monday approval.
Qualifications must stay attached to their source
The blog discusses possible causes of delay, including bank processes and checks required by other obligations. Its separate discussion of identity verification does not mean every delay is justified. Nor does this article decide a dispute or determine which documents an individual must provide.
The deposit-balance guidance addresses restrictions and qualifications in the British regulatory framework. Both sources have a Great Britain context; they do not supply a Canadian operator’s rules or a universal payout deadline.
The timing-statement comparison keeps access and processing apart. The payment-method article concerns the applicable method. The complaints-procedure article concerns a separate process if a question remains unresolved. No account, identity document, payment instrument or private correspondence was accessed for this review.